What Is a Driveby Appraisal and When Is It Used?
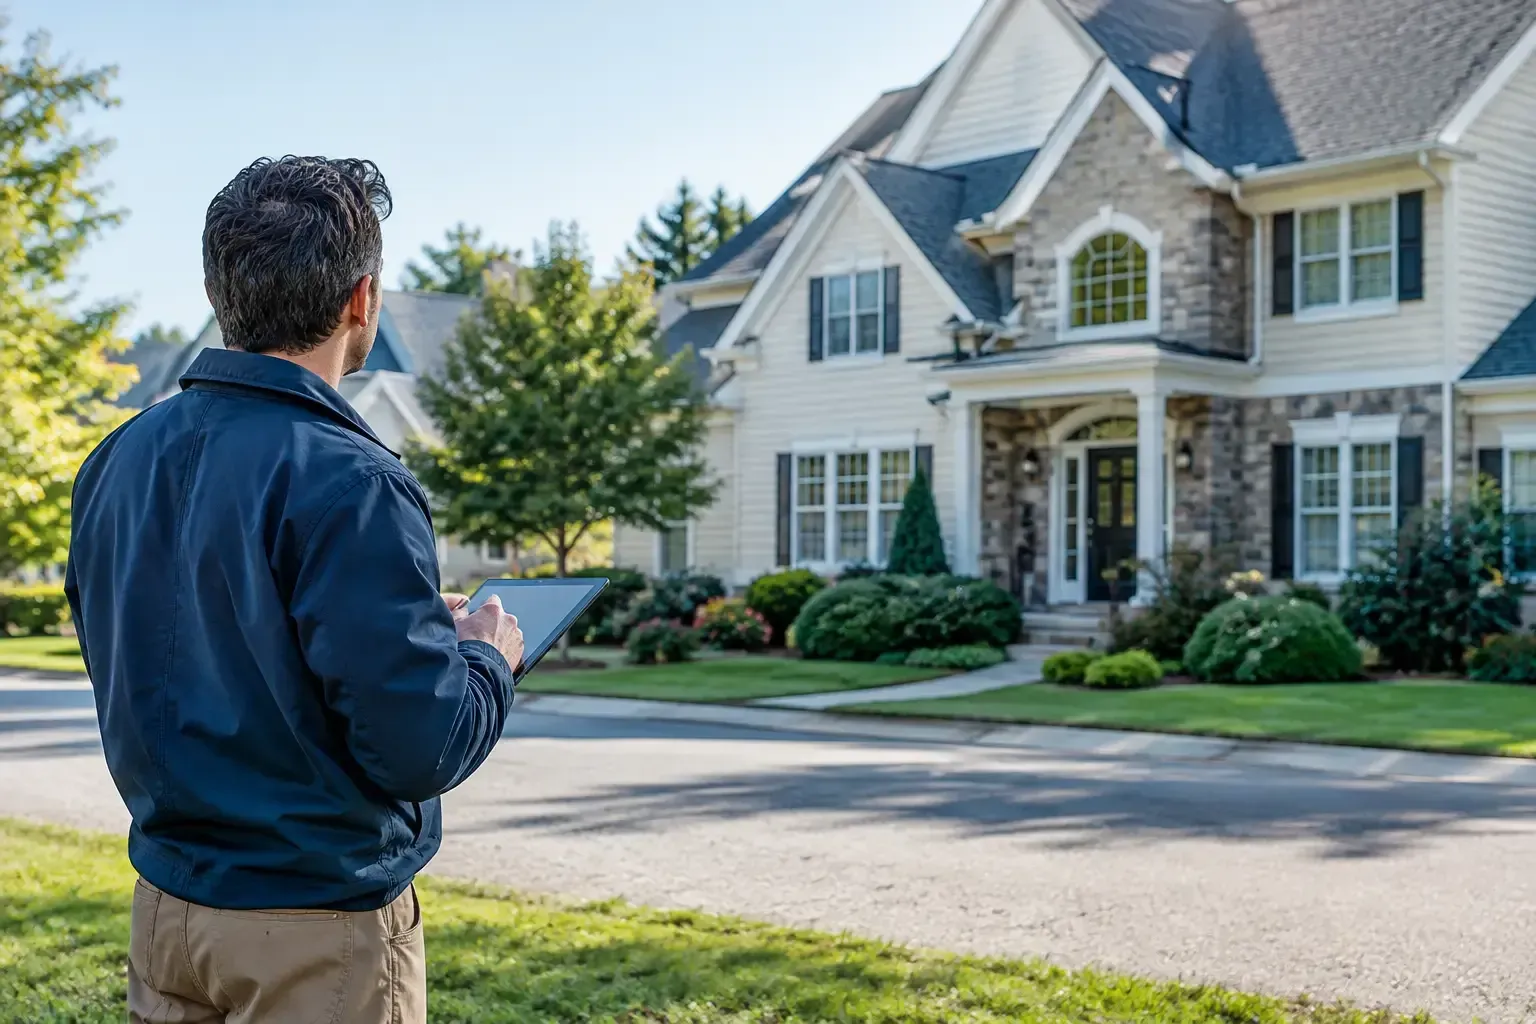
A property can look well maintained from the street while needing extensive work behind the front door. That distinction is central to answering the question, what is a driveby appraisal? A driveby appraisal is an appraisal assignment in which the appraiser inspects the property's exterior but does not enter the home. The appraiser then develops an opinion of value using the exterior observation, public records, market data, and the scope of work required for the assignment.
The name can sound informal, but a driveby appraisal is not a casual pass through the neighborhood or a guess based on a photograph. When completed by a qualified appraiser, it is a formal valuation service with a limited inspection scope. Whether it is appropriate depends on the intended use, the property, the lender or client requirements, and the reliability of available information.
What Is a Driveby Appraisal?
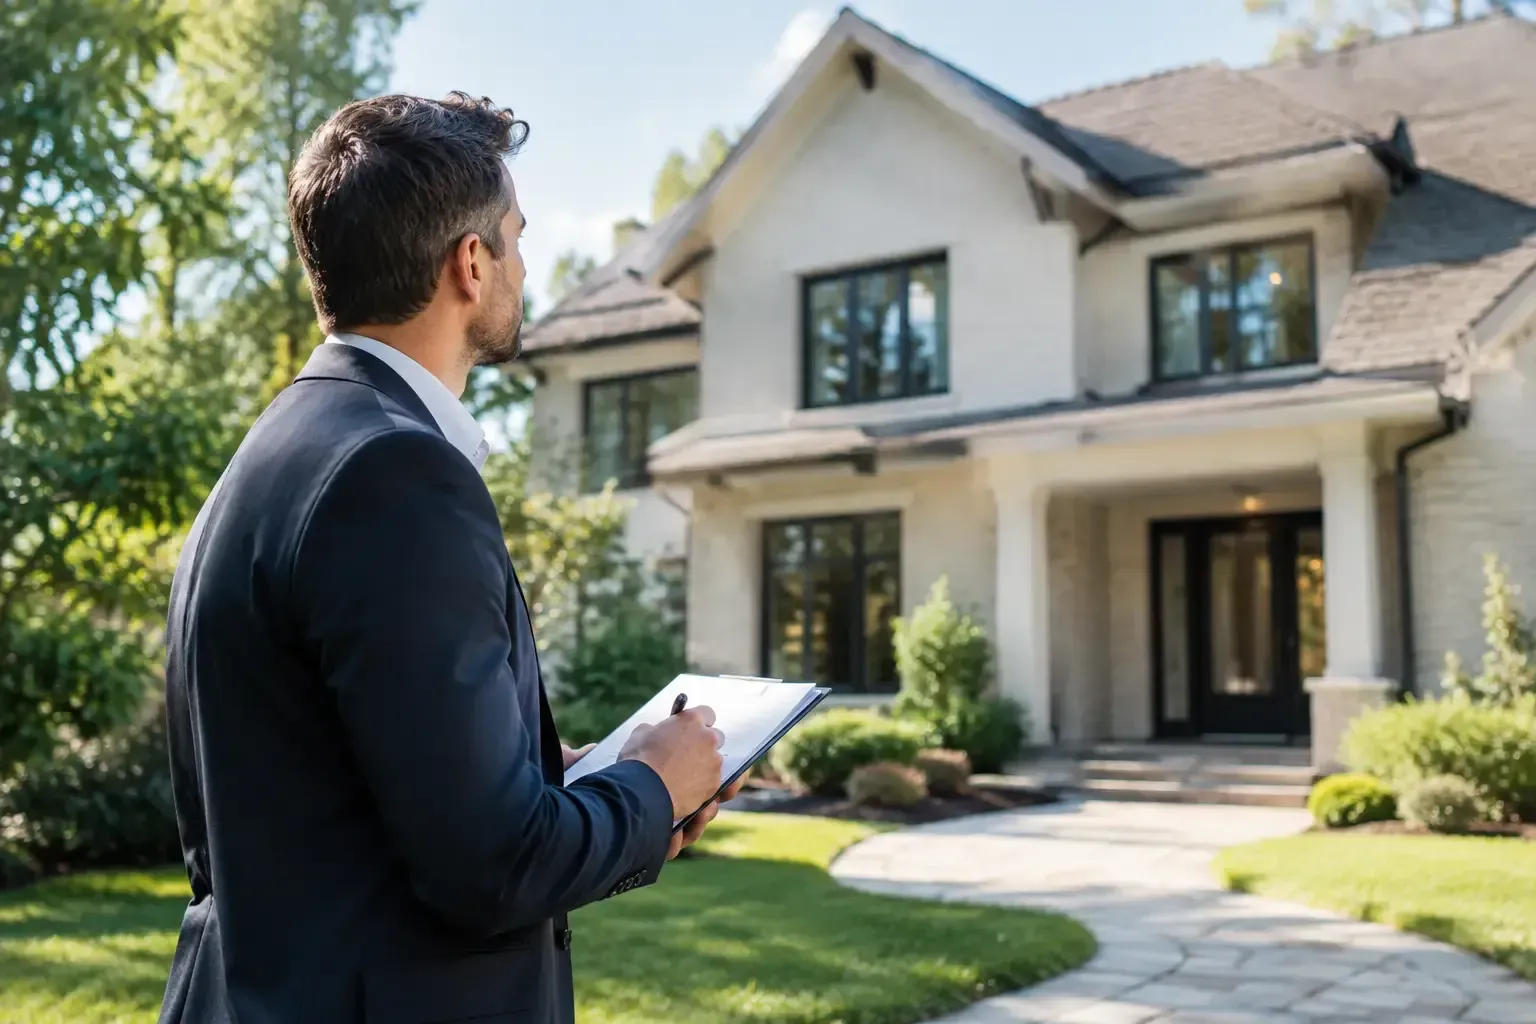
Also called an exterior-only appraisal, a driveby appraisal involves an in-person exterior observation of the subject property. The appraiser typically views the home from the street or another lawful vantage point, confirms observable characteristics, photographs the exterior, and assesses factors that may affect value. These can include apparent condition, site influences, curb appeal, neighborhood setting, exterior updates, access, and visible deferred maintenance.
The appraiser also researches details that cannot be confirmed during the exterior visit. Public records, prior listing information, building data, tax records, market activity, and other credible sources may help establish the home's reported living area, room count, lot size, design, age, and other relevant characteristics.
Because the interior is not inspected, the report must reflect that limitation. The appraiser may rely on extraordinary assumptions or assignment conditions concerning the home's interior condition, features, and updates. Those assumptions are not minor fine print. They can materially affect how much confidence a user should place in the conclusion.
For example, an exterior-only appraisal may assume the interior is in typical condition for the property's age and market segment if there is no reliable evidence to the contrary. If the home actually has a fully renovated kitchen and baths, significant water damage, an unfinished addition, or severe interior deterioration, the value conclusion could differ from what a full interior inspection would support.
How an Exterior-Only Appraisal Is Completed
The appraiser begins by identifying the purpose of the assignment and the client's requirements. A lender may have a specific appraisal product or policy for a refinance or other transaction. A private client may need a valuation for a narrower planning purpose. The required scope of work should be established before the property is inspected.
During the exterior visit, the appraiser observes the home and surrounding area. They may note the architectural style, exterior materials, visible condition, landscaping, driveways, garages, site utility, views, road influences, adjacent land uses, and signs of remodeling or disrepair. They also confirm whether the property appears consistent with the available records.
The valuation analysis still requires market support. Appraisers research comparable sales and make reasoned adjustments for meaningful differences between the subject and comparable properties. In markets such as Long Island, New York City, Fairfield County, or the Midlands of South Carolina, local knowledge matters. Property values can change substantially from one neighborhood, school district, waterfront area, or municipality to the next.
The final report identifies the inspection scope and describes the information used. A credible report does not pretend that an exterior-only observation provides the same level of certainty as a full appraisal. It explains what was observed, what was assumed, and how those facts affected the analysis.
When Is a Driveby Appraisal Used?
Driveby appraisals are most often associated with certain lending situations, particularly when a lender's underwriting guidelines permit an exterior-only inspection. The lender, not the homeowner, generally determines whether that product is eligible for a specific loan transaction. Eligibility can depend on the loan type, borrower profile, property characteristics, automated underwriting findings, and current investor requirements.
They may also be considered when interior access is impractical, although limited access does not automatically make an exterior-only appraisal appropriate. A property with unusual construction, major visible concerns, incomplete renovations, conflicting records, or limited comparable sales may require a more comprehensive inspection instead.
For homeowners, attorneys, and financial professionals, the intended use is especially important. An exterior-only appraisal may not provide the level of support needed for a divorce matter, estate settlement, tax appeal, litigation, bankruptcy, or a high-stakes private sale. Those assignments often require a thorough property inspection, detailed reporting, retrospective analysis, or a report designed to withstand review by opposing parties, courts, or government agencies.
A quick process is valuable only when it produces an appraisal that fits the decision being made. Choosing a limited-scope appraisal for a matter that demands a fully supported interior analysis can create avoidable delays and expense later.
Driveby Appraisal vs. Full Appraisal
The primary difference is the inspection. In a full appraisal, the appraiser enters the home and observes its interior layout, condition, quality, updates, functional utility, and features that influence marketability and value. The appraiser can verify items such as the number of bedrooms and bathrooms, finished basement areas, kitchen and bath renovations, flooring, mechanical systems where visible, and evidence of deferred maintenance.
A driveby appraisal does not offer that direct verification. It can still be credible for the right assignment, but it carries a greater reliance on records and assumptions. That is a practical trade-off, not a defect. If the property is relatively typical, records are reliable, and the intended use allows exterior-only scope, the approach may be sufficient. If interior condition is a central value driver, the limited scope may not be enough.
A desktop appraisal is different as well. A desktop appraisal may be completed without the appraiser physically visiting the property at all. It relies on data, imagery, documents, and market research. A driveby appraisal includes an exterior observation, which can provide useful confirmation of the property's existence, apparent condition, setting, and visible characteristics.
What Homeowners Should Know Before an Exterior-Only Appraisal
If your lender orders a driveby appraisal, ask whether you need to do anything before the appointment. Because the appraiser may not need access to the home, you may not need to be present. Still, keeping the exterior accessible and the house number visible can help the inspection proceed efficiently.
Do not assume that an exterior-only appraisal gives the appraiser a complete picture of improvements you have made. If a lender or client permits additional property information to be considered, documentation for a new roof, solar installation, permitted addition, or major renovation may be useful. The appraiser must independently determine what information is credible and relevant under the assignment conditions.
It is also wise to understand that a driveby appraisal is not a home inspection. Appraisers develop opinions of market value. They do not test systems, identify every repair issue, guarantee condition, or provide a code-compliance review. If you are purchasing a home or evaluating a property's physical condition, a qualified home inspection serves a different purpose.
When a Full Interior Appraisal Is the Better Choice
A full appraisal is generally the stronger option when the interior is likely to have a meaningful effect on value or when the report will be used in a formal, potentially contested setting. This is common for estates, date-of-death valuations, divorce and equitable distribution, bankruptcy, property tax challenges, pre-listing decisions, and expert witness work.
It is also appropriate when a home has substantial renovations, unusual features, condition issues, an accessory dwelling unit, a complex site, or limited comparable sales. In these situations, direct observation allows the appraiser to explain the property accurately rather than rely on incomplete records or broad assumptions.
Connect Appraisal helps clients determine the appraisal scope that best supports their intended use, whether the assignment involves lending, planning, settlement, or litigation. The right report is not simply the fastest report available. It is the one with the inspection level, analysis, and documentation needed for the decision in front of you.
A driveby appraisal can be an efficient and credible valuation tool when its limitations match the assignment. Before relying on one, make sure the scope fits the stakes, the property, and the people who will need to rely on the final opinion of value.
Client Connect Blog